

How to track labor vs. material cost variance by project
Published:
Cost variance in residential construction is the single largest driver of profit erosion, but labor variance and material variance stem from fundamentally different operational breakdowns.
Material variance is driven by price volatility, site waste and unbilled scope expansion.
Labor variance is driven by crew productivity rates, trade partner scheduling friction and inaccurate labor burdening. According to industry research from the APB State of Residential Construction Industry report, 78% of residential contractors who suffer budget overruns fail to catch cost code variances until invoices arrive weeks after field work is completed.
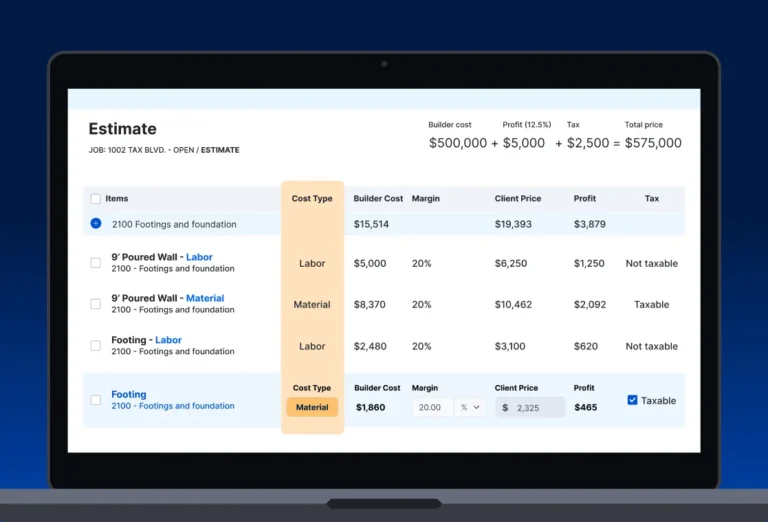
To eliminate profit leaks, custom home builders and residential remodelers need to isolate labor vs. material variances in real time using standardized CSI cost codes, mobile daily time tracking, pre-approved purchase orders and automated variance threshold alerts powered by Buildertrend financial management tools.
Defining cost variance: Labor vs. material variance dynamics
In custom home building and residential remodeling, a project budget isn’t a static financial document. It’s a live operational baseline. How to calculate job costs in residential construction establishes that tracking actual spending against estimated cost code allocations is mandatory for margin survival. But treating every cost overrun as a generic “budget leak” blinds contractors to the distinct root causes driving profit erosion.
Cost variance is mathematically defined as the difference between the estimated baseline budget for a specific scope item and the actual cost incurred upon execution. It’s expressed in both total dollar value and percentage deviation:
Core cost variance formulas
- Total cost variance ($) = actual cost incurred − estimated budgeted cost
- Percentage cost variance (%) = [(actual cost − estimated cost) ÷ estimated cost] × 100
- Labor efficiency variance = (actual hours worked − estimated hours budgeted) × fully burdened hourly rate
- Labor rate variance = (actual fully burdened hourly rate − estimated hourly rate) × actual hours worked
- Material price variance = (actual unit price − estimated unit price) × actual quantity purchased
- Material quantity/waste variance = (actual quantity used − estimated quantity) × baseline unit price
The fundamental divide: Why labor and material variances behave differently
To control project budgets, field managers and office accountants need to analyze labor and material variances independently. They follow completely different operational rules:
- Material cost variance (price and quantity driven): Material variance happens when physical supplier purchases exceed baseline estimates. It breaks into two sub-components: material price variance (paying $4.20 per stud instead of the estimated $3.60) and material quantity/waste variance (ordering 1,200 studs due to site waste when 1,000 were estimated). Material variance is driven mainly by external vendor pricing, supply chain volatility and site storage damage.
- Labor cost variance (rate and productivity driven): Labor variance happens when the total cost of field execution deviates from baseline labor allocations. It breaks into labor rate variance (paying an unburdened $32 an hour wage instead of a fully burdened $45 an hour rate that includes taxes and benefits) and labor efficiency variance (taking 120 crew hours to frame a floor plan budgeted for 80 hours). Labor variance is inherently human, highly volatile and directly influenced by site supervision, weather and trade scheduling efficiency.
As detailed in our comparison of construction job costing vs. general accounting, standard bookkeeping tools group labor and materials into broad cost of goods sold accounts. That obscures the real root causes. A builder might see framing costs hit budget overall, unaware that a 15% material savings compensated for a catastrophic 30% labor efficiency loss, a hidden productivity flaw that will collapse margins on the next build.
Primary operational causes of variance in residential construction
Field research across thousands of custom builders points to seven primary operational breakdowns that drive budget overruns. Isolating these root causes lets contractors deploy targeted fixes.
Material variance drivers
- Unlogged scope creep and field change orders. When clients request material upgrades or layout changes directly on site, superintendents often execute the work without generating a formal change order. Unlogged scope expansion is the single largest source of material variance. Using construction change order software ensures all material additions are estimated and client-approved before fulfillment.
- Stale supplier quotes and price volatility. Estimating jobs using six-month-old supplier quotes exposes projects to immediate price variance once material takeoff arrives. High-performing builders link their estimating databases to live vendor pricing feeds.
- Site damage, improper storage and excess scrap. Poor site logistics lead to lumber warping, drywall moisture damage and high scrap ratios, forcing unplanned reorders that balloon material quantities. Intricate architectural details, such as custom tile layouts, frequently generate 15% to 20% scrap ratios that need to be budgeted accurately.
Labor variance drivers
- Inaccurate labor burden calculations. Failing to include payroll taxes, workers’ compensation insurance, health benefits, retirement matches and tool allowances in internal labor rates creates instant, artificial labor overruns on every self-performed hour.
- Trade partner stacking and field inefficiencies. Overcrowding sub-trades in tight residential footprints causes productivity bottlenecks where carpenters, electricians and plumbers get in each other’s way, driving up billable hours.
- Rework driven by architectural misinterpretation. Ambiguous plan specs lead to incorrect rough-in locations, requiring teardowns and reframing that double field labor hours on affected cost codes.
- Lack of real-time daily time tracking. Relying on paper weekly timesheets or verbal memory creates data entry lag. Supervisors can’t address labor slippage until weeks after the budget is burned. Implementing mobile daily logs and time tracking gives field managers instant visibility into daily crew burn rates.
Step-by-step software setup for tracking cost variance
To track labor and material variance automatically, builders need to configure their digital management system to capture field data cleanly. Here’s the five-step setup protocol used in construction budgeting software:
- Step 1: Standardize CSI cost code structure. Set up a unified cost code structure separating labor, materials, equipment and subcontracts for every trade phase (for example, cost code 06-110 for framing labor vs. cost code 06-120 for framing materials). This granularity keeps labor overruns from hiding inside material savings.
- Step 2: Build assemblies with fully burdened rates. Input fully burdened labor rates into your estimating database so every estimated hour reflects true company cost. Lock in vendor material assembly prices before contract execution to establish baseline price integrity.
- Step 3: Enforce purchase order commitment control. Issue binding digital purchase orders for every material order and trade partner contract. POs lock in committed costs, preventing vendors from billing above approved amounts without formal change orders.
- Step 4: Deploy geofenced mobile time tracking. Equip field crews with a mobile app that enforces clock-in and clock-out mapped directly to specific job cost codes. Geofencing ensures crews clock into the correct job site, eliminating miscoded labor hours.
- Step 5: Integrate accounting sync for instant invoice capture. Connect your field management platform to QuickBooks, Xero or Sage Intacct via Buildertrend accounting software integrations. OCR bill capture extracts line-item vendor bills and matches them against open POs instantly.
Sample cost variance analysis: Custom kitchen remodel case study
To see how labor vs. material variance analysis works in practice, consider a $120,000 custom kitchen and main-floor remodel executed by Premier Remodeling Specialists. Here’s the line-item cost variance report across key phase cost codes:
| Cost code and scope | Est. cost | Act. cost | Variance ($) | Variance (%) | Primary driver | Corrective action taken |
|---|---|---|---|---|---|---|
| 02-400 Demolition labor | $3,200 | $4,400 | +$1,200 | +37.5% | Labor efficiency | Updated labor assembly hours for plaster walls. |
| 06-120 Framing materials | $4,500 | $4,100 | -$400 | -8.9% | Material price | Lumber price drop and efficient lumber layout. |
| 06-110 Framing labor | $5,800 | $7,200 | +$1,400 | +24.1% | Labor efficiency | Structural beam installation required extra rig. |
| 12-300 Custom cabinetry | $28,000 | $28,000 | $0 | 0.0% | Locked vendor PO | Pre-approved PO prevented price increase. |
| 22-100 Plumbing rough-in | $6,400 | $7,800 | +$1,400 | +21.9% | Unlogged change | Client shifted sink location; issued CO #1. |
| 09-300 Tile and finish mat. | $8,200 | $9,600 | +$1,400 | +17.1% | Material scrap | Intricate herringbone pattern created 20% scrap. |
Key case study insight: Total project material variance was limited to a modest +$1,000 net overrun, thanks to lumber savings offsetting tile scrap. But total labor variance exploded by +$2,600 (+28.8% above budget). In a traditional general ledger P&L, this labor efficiency loss would be masked. Line-item variance tracking let Premier Remodeling bill $1,400 back to the client via change order #1 for the relocated plumbing sink and adjust future demolition labor estimating assemblies by 35%.
Variance threshold rules and automated alert workflows
To keep variance data from becoming overwhelming, high-performing builders put automated threshold rules in place. Instead of reviewing hundreds of line items daily, managers get automated alerts only when cost codes cross predefined variance boundaries:
- Green zone (0% to 3% variance): Acceptable operational fluctuation. No management intervention required.
- Yellow alert zone (3.1% to 7.5% variance): Triggers an automated push notification to the project manager. Requires field verification of remaining work hours and material counts within 24 hours.
- Red critical threshold (more than 7.5% variance or more than $1,000 absolute overrun): Requires immediate executive notification. Blocks further purchase order issuing on that cost code until a corrective action plan or client change order is approved by the general manager.
Building variance threshold monitoring directly into monthly WIP schedules for residential builders ensures overbilling liabilities and underbilling assets reflect true site progress, maintaining financial health across multi-project portfolios as covered in our guide to job costing benchmarks for residential contractors and in the Buildertrend Modern Builder Playbook.
Operational process checklist for field and office teams
Weekly cost variance control checklist
Pre-construction and setup phase:
- Confirm all line items use standardized labor vs. material CSI cost codes.
- Verify internal labor rates reflect fully burdened costs (taxes, benefits, insurance).
- Lock baseline estimates and issue digital purchase orders to all trade partners.
Weekly field operations phase:
- Require field crews to clock in and out via mobile geofenced time tracking daily.
- Review daily logs to verify reported labor hours match physical site progress.
- Issue digital change orders immediately upon client request; halt work until approved.
Weekly office and accounting review:
- Scan and process supplier bills using OCR bill capture matched against open POs.
- Run automated cost code variance reports in Buildertrend; audit all red threshold alerts.
- Sync verified job costs to QuickBooks/Xero and update monthly WIP schedules.
Frequently asked questions
Top-performing residential builders target an overall project variance of less than plus or minus 3%. At the cost code level, individual variances exceeding 5% or $1,000 should trigger an immediate management review to determine if corrective action or a change order is required.
If a contractor estimates labor using raw wages ($30 an hour) but pays taxes and benefits that bring the true cost to $45 an hour, every logged labor hour automatically creates a false 50% rate variance. Using fully burdened rates ensures labor variance reflects actual crew efficiency rather than accounting discrepancies.
Yes. Material variance includes both unit price variance and quantity/scrap variance. Tracking scrap rates lets estimators adjust waste factors, such as increasing tile waste allowance from 10% to 15% for complex layouts, on future estimates.
Buildertrend separates labor, material and subcontract items within standardized cost codes. It captures live labor via mobile time tracking and material spend via PO invoice matching, generating real-time budget vs. actual variance reports automatically.
The superintendent should pause uncommitted spending on that cost code, conduct an immediate site count of remaining work, determine whether the overrun was caused by an unlogged scope change and submit a client change order or management mitigation plan before proceeding.